
Alpine Saxon Woods Dividend Strategy
Overview
The Dividend strategy invests in companies that have maintained or increased dividends for at least the past 5 years. Fundamental research is performed on each company’s ability to sustain its dividend and potentially increase those payments in the future, incorporating analysis on free cash flow and numerous balance sheet metrics. The strategy is market capitalization and sector agnostic, but the nature of dividend paying companies tends to tilt towards a mid-to-large capitalization profile.
Investment Objectives
The objective of the Strategy is to generate high current income, growth of income, and capital preservation by investing in high-quality companies that pay attractive dividends and have the potential to increase those dividends over time. This approach aims to provide consistent returns, especially during market volatility.
Portfolio Construction
The portfolio is constructed using liquid, publicly traded stocks and is typically fully invested. Positions are generally initiated at weights of 3% to 5%, with the portfolio normally holding between 35 and 45 securities. To maintain diversification and manage risk, individual security positions are generally limited to no more than 10% of portfolio assets, while sector exposure is limited to 25% of the portfolio or 1.5 times the benchmark weighting, whichever is greater. Quantitative risk management statistics are regularly reviewed to identify where portfolio risks exist and to evaluate the sources and magnitude of those risks.
Risk management is an ongoing component of the investment process. Portfolio holdings are continuously monitored, and investment theses are formally reviewed when a stock declines 15% from its initial purchase price. This review is intended to determine whether the original investment rationale remains intact and whether the risk-reward profile continues to be attractive.
Securities may be sold for several reasons, including changes in company fundamentals, deterioration in operating or financial health, or when the original investment thesis is no longer valid. Positions may also be exited when anticipated catalysts fail to materialize or are no longer expected to drive future value creation. In addition, holdings may be reduced or eliminated when they reach the team's valuation target. Portfolio diversification guidelines, including individual security and sector exposure limits, are also considered as part of the sell discipline and ongoing portfolio management process.


No items found.
Quick Facts
As of
September 30, 2026
Fund
SMA Inception Date
1/1/2019
Benchmark 1
S&P Dividend ETF (SDY)
Benchmark 2
iShares Russell 1000 Value ETF (IWD)
Strategy AUM
$86.10M
Investment Minimum
Negotiable
Fees
Negotiable
Meet the Team
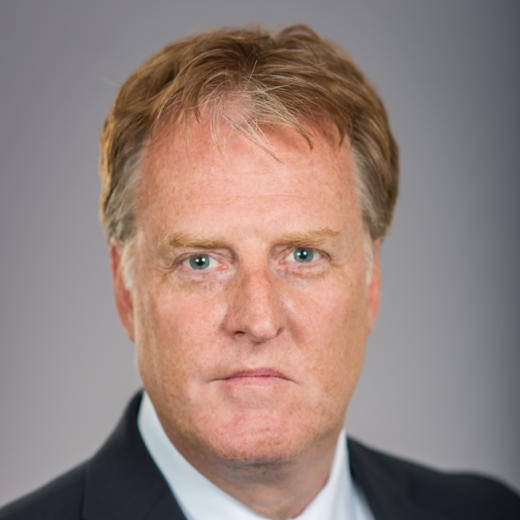
Mark T. Spellman
- 32 years industry experience
- BS: Boston College
- MBA: UMass Amherst
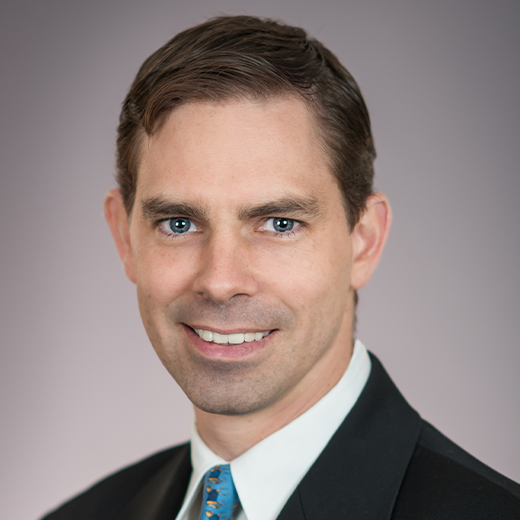
Brian Hennessey, CFA
- 27 years industry experience
- BA: Williams College
- MBA: M.I.T.
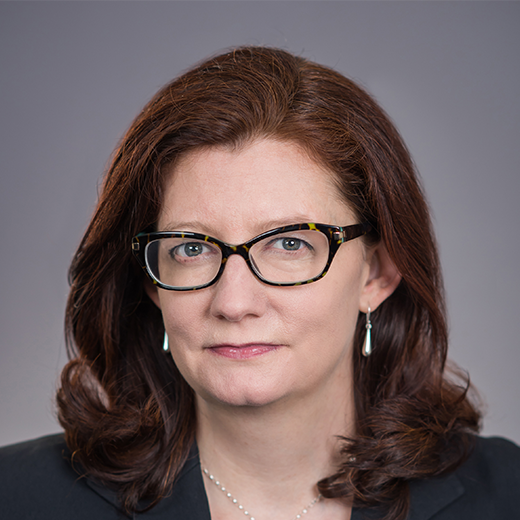
Sarah Hunt, CFA, CFP®
- 26 years industry experience
- BA: Wesleyan University
- MBA: Fordham University
Ronak Jain, CFA
- 17 years industry experience
- BBA: Macaulay Honor College at Baruch College
Characteristics
As of
September 30, 2026
Strategy
Benchmark 1
Number of Holdings
38
155
Median Market Cap ($B)
88.25
20.48
TTM Dividend Yield
2.86
%
2.98
%
1-Year Dividend Growth
6.05
5.41
5-Year Dividend Growth
6.63
6.3
P/E 1-Year Forward
18.19
17.29
Free Cash Flow Yield
4.29
%
4.36
%
Total Debt/EBITDA
3.43
2.97
Annual Turnover
72.15
–
Please see the Glossary for descriptions of these terms.
Sector Analysis
As of
September 30, 2026
Strategy
Benchmark 1
Healthcare
17.4
%
8.4
%
Financials
16.0
%
12.2
%
Technology
14.9
%
8.7
%
Industrials
13.5
%
18.5
%
Consumer Staples
10.1
%
15.9
%
Materials
9.0
%
7.4
%
Real Estate
6.4
%
4.0
%
Utilities
5.4
%
12.9
%
Consumer Discretionary
4.2
%
5.1
%
Energy
3.1
%
3.7
%
Communications
0.0
%
3.2
%
Top 10 Holdings
As of
September 30, 2026
Fund
JPMORGAN CHASE & CO
4.2
%
AMGEN INC
4.1
%
ABBVIE INC
3.8
%
MEDTRONIC PLC
3.8
%
EMERSON ELECTRIC CO
3.7
%
CISCO SYSTEMS INC
3.3
%
WILLIAMS COS INC
3.1
%
ABBOTT LABORATORIES
3.1
%
MONDELEZ INTERNATIONAL INC-A
3.1
%
MICROSOFT CORP
2.9
%
TOTAL
35.1
%
Risk/Returns Metrics
As of
September 30, 2026
Strategy
Benchmark 1
Alpha
3.28
%
–
Beta
0.91
1.00
Sharpe Ratio
0.50
0.31
Standard Deviation
14.25
%
14.61
%
Up/Down Capture
98/85
–
Risk/Return Metrics based on rolling 5-year period measured quarterly. Past performance is no guarantee of future results. Investing involves risks, including the possible loss of
principal.
Please see the Glossary for descriptions of these terms.
Average Annual Total Return
As of
September 30, 2026
As of
October 31, 2026
YTD
1 Year
3 Year
5 Year
Since Inception
Gross
8.80
%
10.80
%
18.03
%
11.10
%
10.90
%
Net (Composite)
8.14
%
9.86
%
16.96
%
10.08
%
9.89
%
Benchmark 1
7.24
%
7.33
%
11.26
%
7.28
%
9.49
%
Benchmark 2
19.12
%
23.67
%
19.86
%
11.73
%
13.21
%
YTD
1 Year
3 Year
5 Year
Since Inception
Gross
16.38
%
18.26
%
22.03
%
11.37
%
11.73
%
Net (Composite)
15.39
%
17.25
%
20.92
%
10.32
%
10.69
%
Benchmark 1
17.66
%
20.19
%
15.79
%
8.28
%
10.69
%
Benchmark 2
24.27
%
28.40
%
23.03
%
11.56
%
13.67
%
Past performance is no guarantee of future results. Investing involves risks, including the possible loss of the principal amount invested. The use of Alpine Saxon Woods does not eliminate risks associated with investing. Consider the investment objectives, risks, charges, and expenses carefully before investing. The information presented has been obtained from sources believed to be reliable, but its accuracy and completeness are not guaranteed. Opinions, estimates and projections constitute the judgment of Alpine Saxon Woods and are subject to change without notice. This material is presented for informational purposes only and is not an offer, recommendation or solicitation regarding any financial product or service or as a determination that any investment strategy is suitable for a specific investor. Investors should seek financial advice regarding the suitability of any investment strategy based on the investor’s objectives, financial situation and particular needs. The investments or investment strategies discussed may not be suitable for every investor. There is no assurance that any investment strategy will be successful. Some investment products may be available only to certain “qualified investors” — that is, investors who meet certain income and/or investable assets thresholds.
Performance is presented both gross and net of composite fees. The highest fee applicable for a separate account managed directly by Alpine Saxon Woods is 1.0% annually. (Strategies accessed through third-party wrap programs will pay fees as high as 3%.) Gross-of-fee returns reflect the impact of transaction costs but not the deduction of advisory fees. Net-of-fee (Net) returns reflect the deduction of all transaction costs and advisory fees to accounts in the composite. Actual fees and account minimums may vary. Indices, including index ETFs, are provided solely for illustrative purposes. Indices are not available for direct investment, and do not reflect the deduction of fees and trading costs, which would reduce returns. ETFs are similarly provided to illustrate particular industries or industry groups and are not recommendations for investment. ETF fees and expenses are lower (typically 0.10%-0.35%) than is typical for a managed account, which can exceed 1%.
The positions provided represent holdings as of the date shown and are subject to change without notice. Reported positions do not include all securities that were purchased, sold or held in client accounts over time. It should not be assumed that the holdings described are or will be profitable or that securities purchased in the future will be profitable or will equal the performance of the securities in this list. References to specific securities do not represent a recommendation to purchase or sell any particular security outside a managed account.
The Quarter's Top Contributors
As of
September 30, 2026
Software behemoth Microsoft (MSFT) was a top contributor in the quarter. The company reported better-than expected sales and earnings, putting investors’ minds at ease over its massive AI capital spending program. Its Azure cloud business showed revenue accelerating while its AI assistant Copilot showed better-than-expected commercial rollout results. These results illustrated the potential ROI for its capital spending plan. We continue to like the MSFT story as it begins to show tangible financial results of how it is benefiting from its AI spending. Biotech drug firm Amgen (AMGN) was also a top contributor during the quarter. AMGN reported better than expected revenue and earnings and is on pace to generate more than $10B in free cash flow for 2026. Test results for its once-a-month obesity drug, MariTide, were positive and could give it a unique entry into the obesity market. Early Phase III results for its autoimmune disease drug were also positive and could conceivably give it a new path for entry into the treatment of numerous autoimmune diseases. We continue to like AMGN given its recent execution and robust R&D pipeline. Shares of Garmin (GRMN) were also a major contributor in the quarter. Record sales in its fitness division that handily beat expectations, coupled with significantly higher gross and operating margins, drove the shares higher as the company raised expectations for 2027. Its acquisitions in the premium endurance and training segments are further solidifying its strength in personal fitness.
The Quarter's Top Detractors
As of
September 30, 2026
Diesel engine and power unit producer Cummins (CMI) also underperformed in the quarter due to weakness in the aforementioned AI-related trade. As with LRCX, its results and order book remain strong but sentiment turned against the theme in 3Q. We continue to like the prospects for CMI and continue to hold the shares. Shares of Brookfield Renewable (BEPC), which were purchased earlier in 3Q, detracted from the strategy’s performance for the quarter. While we feel the healthy 5.56% dividend yield is attractive, interest rate spikes late in the quarter hurt most utilities and dividend-paying stocks. We still see good value in BEPC and continue to hold shares, despite our mistiming of its initial purchase. Defense contractor L3Harris (LHX) underperformed for the second consecutive quarter after starting off the year strongly when it benefited from war in the Middle East. The prospects for the end of hostilities and slower defense budget growth caused weakness in the shares. Its CEO was also fired during the quarter after an investigation into his personal conduct. We sold our entire position in LHX during the quarter as the company looks to get back on track in several capacities.
About the Top Guns Award
Alpine Saxon Woods’ Dividend Strategy earned PSN Top Guns, 4-Star. 5-Star, and 6-Star awards. Alpine Saxon Woods pays no compensation to PSN for its consideration for the Top Guns, but does pay a nominal fee for the rights to use the PSN Top Gun name and badges in its own marketing. These Top Gun ratings are awarded based on performance reported by Alpine Saxon Woods to PSN. Through a combination of PSN’s proprietary performance screens, the PSN Top Guns awards investment strategies in six categories across more than 75 universes. PSN employs proprietary benchmark and peer group metrics, including correlation, volatility, performance, and information ratio, for the All Cap Value style as described below.
4-Star Top Gun: had an r-squared (r2 or correlation squared) of 0.80 or greater relative to PSN’s All Cap Value style benchmark for the recent five-year period. Moreover, the strategy’s returns exceeded the style benchmark for the three latest three-year rolling periods and was among the top ten returns for the latest three-year period.
5-Star Top Gun: meets the above benchmark correlation and relative returns criteria as well as overall volatility (as measured by standard deviation) equal to or less than the median standard deviation for PSN’s All Cap Value peer group for the prior five-year period. The top ten returns for the latest three-year period among qualifying All Cap Value peers then become the 5 Star Top Guns.
6-Star Top Gun: meets the above benchmark correlation, relative return, and volatility criteria above and represent the top ten information ratios among qualifying All Cap Value peers for the latest five-year period.
The information contained on this website is the property of Alpine Saxon Woods LLC (“ASW”) and is being provided for information purposes only. This website and the information contained herein is not an offer to sell or the solicitation of an offer to buy any securities or instruments, or a recommendation, representation of suitability or endorsement of any security or investment. Since ASW cannot anticipate all the requisites of each individual viewer, there is no consideration given for the specific investment needs, objectives or risk tolerance of any viewer. ASW’s services are primarily provided through separately managed accounts. Some ASW investment products may be available only to certain “qualified investors”—that is, investors who meet certain income and/or investable assets thresholds – and are offered only pursuant to confidential offering documents. Before making any investment decision, individuals should consult their own advisors, including legal and tax advisors.