Alpine Saxon Woods Capital Return Strategy
Overview
Our Capital Return Strategy focuses on identifying financially sound companies with a demonstrated history of paying and raising dividends alongside meaningful share repurchase programs. We prioritize well-capitalized firms led by management teams committed to growing free cash flow, which supports sustained dividend increases and share buybacks. We carefully evaluate each stock’s current valuation against its historical range and future growth prospects to determine its attractiveness.
Investment Objectives
Our Strategy focuses on total return through capital appreciation and income. We achieve this by investing in U.S. stocks with high free cash flow that pay dividends and have a meaningful stock repurchase program.
Portfolio Construction
When constructing a portfolio, a disciplined framework guides every investment decision. The process begins with a focus on liquidity, ensuring that only stocks with sufficient trading volume are considered. This provides flexibility and reduces the risk associated with holding illiquid securities.
Each position in the portfolio typically represents 2% to 5% of the total assets, promoting diversification while allowing for conviction in individual ideas. The portfolio usually holds between 30 and 45 securities, striking a balance between concentration and diversification.
To maintain prudent risk exposure, no single security is allowed to comprise more than 10% of the total portfolio. Similarly, sector exposure is carefully managed, generally capped at 25% of the portfolio or 1.5 times the sector’s weight in the benchmark, whichever is greater. This ensures that sector biases do not unduly influence performance.
The portfolio is typically fully invested, reflecting a commitment to staying engaged in the market rather than attempting to time it.
Risk management is an ongoing priority. Quantitative tools are regularly used to review risk statistics, helping to identify where risks exist and in what forms they may be present—whether at the security, sector, or portfolio level. This data-driven approach supports informed decision-making and portfolio resilience through varying market conditions.
Quick Facts
As of
September 30, 2026
Fund
SMA Inception Date
1/1/2019
Benchmark 1
S&P Dividend ETF (SDY)
Benchmark 2
iShares Russell 1000 Value ETF (IWD)
Strategy AUM
$21.41M
Investment Minimum
Negotiable
Fees
Negotiable
Meet the Team
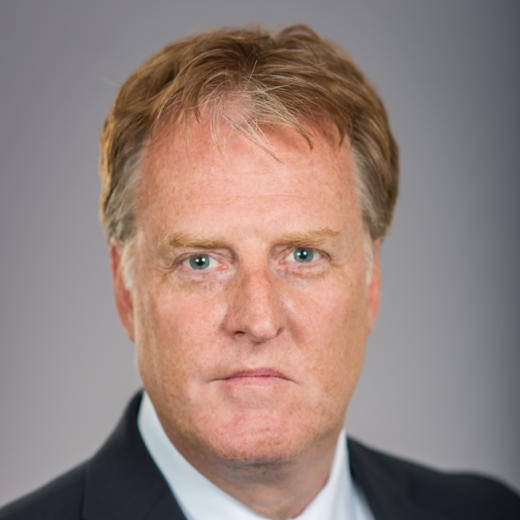
Mark T. Spellman
- 32 years industry experience
- BS: Boston College
- MBA: UMass Amherst
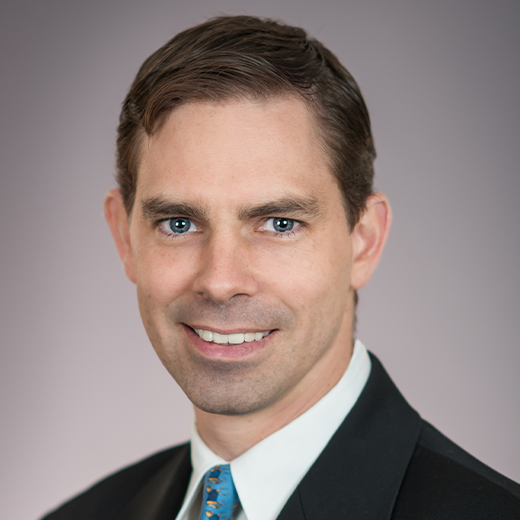
Brian Hennessey, CFA
- 27 years industry experience
- BA: Williams College
- MBA: M.I.T.
Sarah Hunt, CFA, CFP®
- 26 years industry experience
- BA: Wesleyan University
- MBA: Fordham University
Ronak Jain, CFA
- 17 years industry experience
- BBA: Macaulay Honor College at Baruch College
Characteristics
As of
September 30, 2026
Strategy
Benchmark 1
Number of Holdings
32
155
Median Market Cap ($B)
100.66
20.48
TTM Dividend Yield
1.58
%
2.98
%
3-Year Dividend Growth
10.24
6.82
5-Year Dividend Growth
10.91
6.3
P/E 1-Year Forward
19.69
17.29
Free Cash Flow Yield
3.87
%
4.3
%
Total Debt/EBITDA
2.22
2.97
Annual Turnover
64.8
–
Please see the Glossary for descriptions of these terms.
Sector Analysis
As of
September 30, 2026
Strategy
Benchmark 1
Technology
19.3
%
8.7
%
Financials
16.0
%
12.2
%
Industrials
14.7
%
18.5
%
Healthcare
13.8
%
8.4
%
Consumer Discretionary
8.5
%
5.1
%
Energy
7.5
%
3.7
%
Materials
6.0
%
7.4
%
Consumer Staples
5.3
%
15.9
%
Utilities
4.5
%
12.9
%
Communications
4.4
%
3.2
%
Real Estate
0.0
%
4.0
%
Top 10 Holdings
As of
September 30, 2026
Fund
MICROSOFT CORP
5.6
%
JPMORGAN CHASE
4.6
%
ALPHABET INC-C
4.4
%
PHILLIPS 66
4.3
%
APPLE INC
4.2
%
AMGEN INC
4.0
%
DANAHER CORP
3.9
%
ELI LILLY & CO
3.9
%
NORTHROP GRUMMAN
3.5
%
CHENIERE ENERGY
3.3
%
TOTAL
41.7
%
Risk/Returns Metrics
As of
September 30, 2026
Strategy
Benchmark 1
Alpha
2.30
%
–
Beta
0.85
1.00
Sharpe Ratio
0.40
0.31
Standard Deviation
13.65
%
14.61
%
Up/Down Capture
92/84
–
Risk/Return Metrics based on rolling 5-year period measured quarterly. Past performance is no guarantee of future results. Investing involves risks, including the possible loss of
principal.
Please see the Glossary for descriptions of these terms.
Average Annual Total Return
As of
September 30, 2026
As of
September 30, 2026
YTD
1 Year
3 Year
5 Year
Since Inception
Gross
11.83
%
12.06
%
15.42
%
9.47
%
12.76
%
Net (Composite)
11.05
%
11.08
%
14.39
%
8.52
%
11.79
%
Benchmark 1
7.24
%
7.33
%
11.26
%
7.28
%
9.49
%
Benchmark 2
19.12
%
23.67
%
19.86
%
11.73
%
13.21
%
YTD
1 Year
3 Year
5 Year
Since Inception
Gross
11.83
%
12.06
%
15.42
%
9.47
%
12.76
%
Net (Composite)
11.05
%
11.08
%
14.39
%
8.52
%
11.79
%
Benchmark 1
7.24
%
7.33
%
11.26
%
7.28
%
9.49
%
Benchmark 2
19.12
%
23.67
%
19.86
%
11.73
%
13.21
%
Past performance is no guarantee of future results. Investing involves risks, including the possible loss of the principal amount invested. The use of Alpine Saxon Woods does not eliminate risks associated with investing. Consider the investment objectives, risks, charges, and expenses carefully before investing. The information presented has been obtained from sources believed to be reliable, but its accuracy and completeness are not guaranteed. Opinions, estimates and projections constitute the judgment of Alpine Saxon Woods and are subject to change without notice. This material is presented for informational purposes only and is not an offer, recommendation or solicitation regarding any financial product or service or as a determination that any investment strategy is suitable for a specific investor. Investors should seek financial advice regarding the suitability of any investment strategy based on the investor’s objectives, financial situation and particular needs. The investments or investment strategies discussed may not be suitable for every investor. There is no assurance that any investment strategy will be successful. Some investment products may be available only to certain “qualified investors” — that is, investors who meet certain income and/or investable assets thresholds.
Performance is presented both gross and net of composite fees. The highest fee applicable for a separate account managed directly by Alpine Saxon Woods is 1.0% annually. (Strategies accessed through third-party wrap programs will pay fees as high as 3%.) Gross-of-fee returns reflect the impact of transaction costs but not the deduction of advisory fees. Net-of-fee (Net) returns reflect the deduction of all transaction costs and advisory fees to accounts in the composite. Actual fees and account minimums may vary. Indices, including index ETFs, are provided solely for illustrative purposes. Indices are not available for direct investment, and do not reflect the deduction of fees and trading costs, which would reduce returns. ETFs are similarly provided to illustrate particular industries or industry groups and are not recommendations for investment. ETF fees and expenses are lower (typically 0.10%-0.35%) than is typical for a managed account, which can exceed 1%.
The positions provided represent holdings as of the date shown and are subject to change without notice. Reported positions do not include all securities that were purchased, sold or held in client accounts over time. It should not be assumed that the holdings described are or will be profitable or that securities purchased in the future will be profitable or will equal the performance of the securities in this list. References to specific securities do not represent a recommendation to purchase or sell any particular security outside a managed account.
The Quarter's Top Contributors
As of
June 30, 2026
Semiconductor equipment manufacturer Lam Research (LRCX) is a top contributor for the fourth quarter in a row. AI-related spending and tariff worries evident early in 2025 have all but dissipated and LRCX continued to rise posting strong earnings and order books. We continue to own this well-positioned semiconductor equipment manufacturer and believe the industry is well-positioned on a multi-year basis. Semiconductor manufacturer Texas Instruments (TXN) was also a top contributor as the semiconductor industry enjoyed a large rally during the quarter. Companies like TXN, tied to the build-out for AI computing capacity, reported positive results and order outlooks as the data center build out marches on. Drug maker Eli Lilly (LLY), a position initiated during the quarter, was also a top contributor. The company not only reported better-than-expected results in its GLP-1 franchise of Zepbound and Mounjaro, but also for its newly launched daily pill version called Foundayo. Further boosting the shares were some positive Phase III results for its next-generation GLP-1 drug, retatruide. Investors have also been cheered by LLY’s M&A strategy of investing its +$12B in annual free cash flow into companies with products that will diversify its product line-up. The Company has announced purchases of at least eight companies for nearly $20B this year in treatment areas including narcolepsy, cell therapies to treat certain cancers, and infectious diseases and vaccines.
The Quarter's Top Detractors
As of
June 30, 2026
Defense contractors Northrop Grumman (NOC) and L3Harris Technologies (LHX) both underperformed in the quarter after starting off the year strongly when they benefitted from war in the Middle East. The prospects for the end of hostilities caused weakness in the shares as the market rotated back into AI and technology hardware names. We think the outlook for defense procurement is poised to rise for some time and saw the weakness in the shares as an opportunity to increase our exposure. Near the end of the quarter, we increased our positions in both NOC and LHX. 2Q26 Cheniere Energy (LNG) shares slipped during the quarter after starting the year off strongly with the onset of the Middle East war. Shares of the liquefied natural gas supplier benefited in 1Q26 from higher prices (and were a top contributor) brought on by supply disruptions at other producers’ facilities in the Middle East. By 2Q26, similarly to the defense names mentioned earlier, the shares weakened with the prospects of an end to hostilities and a return of Middle East supplies. We reduced our LNG position early in the quarter as momentum began to lag. We think the longer-term prospects for liquefied natural gas production, pricing, and demand growth remains positive, and LNG shares should continue to benefit in spite of any “outbreak of peace”. We continue to hold shares of LNG.
The information contained on this website is the property of Alpine Saxon Woods LLC (“ASW”) and is being provided for information purposes only. This website and the information contained herein is not an offer to sell or the solicitation of an offer to buy any securities or instruments, or a recommendation, representation of suitability or endorsement of any security or investment. Since ASW cannot anticipate all the requisites of each individual viewer, there is no consideration given for the specific investment needs, objectives or risk tolerance of any viewer. ASW’s services are primarily provided through separately managed accounts. Some ASW investment products may be available only to certain “qualified investors”—that is, investors who meet certain income and/or investable assets thresholds – and are offered only pursuant to confidential offering documents. Before making any investment decision, individuals should consult their own advisors, including legal and tax advisors.